Maisie Ewan
Tips for a Smooth Online Title Loan Application Experience
Some lenders may also ask for vehicle insurance information or references, particularly for larger loan amounts. None of this guarantees approval, since every lender in the network sets its own underwriting standards, but arriving prepared removes one of the more common causes of delay.What Happens During the Online Application and Lender-Matching Process Applying for car title loans online through a referral platform generally starts with a short form covering your vehicle details, income information, and contact details. Loans Inc. itself is not a lender; it operates as a connection point that submits your information to a network of participating lenders who independently review applications and make their own approval decisions. This distinction matters for repayment planning because it means the specific interest rate, fee structure, and repayment schedule you're offered will vary depending on which lender in the network extends you an offer.
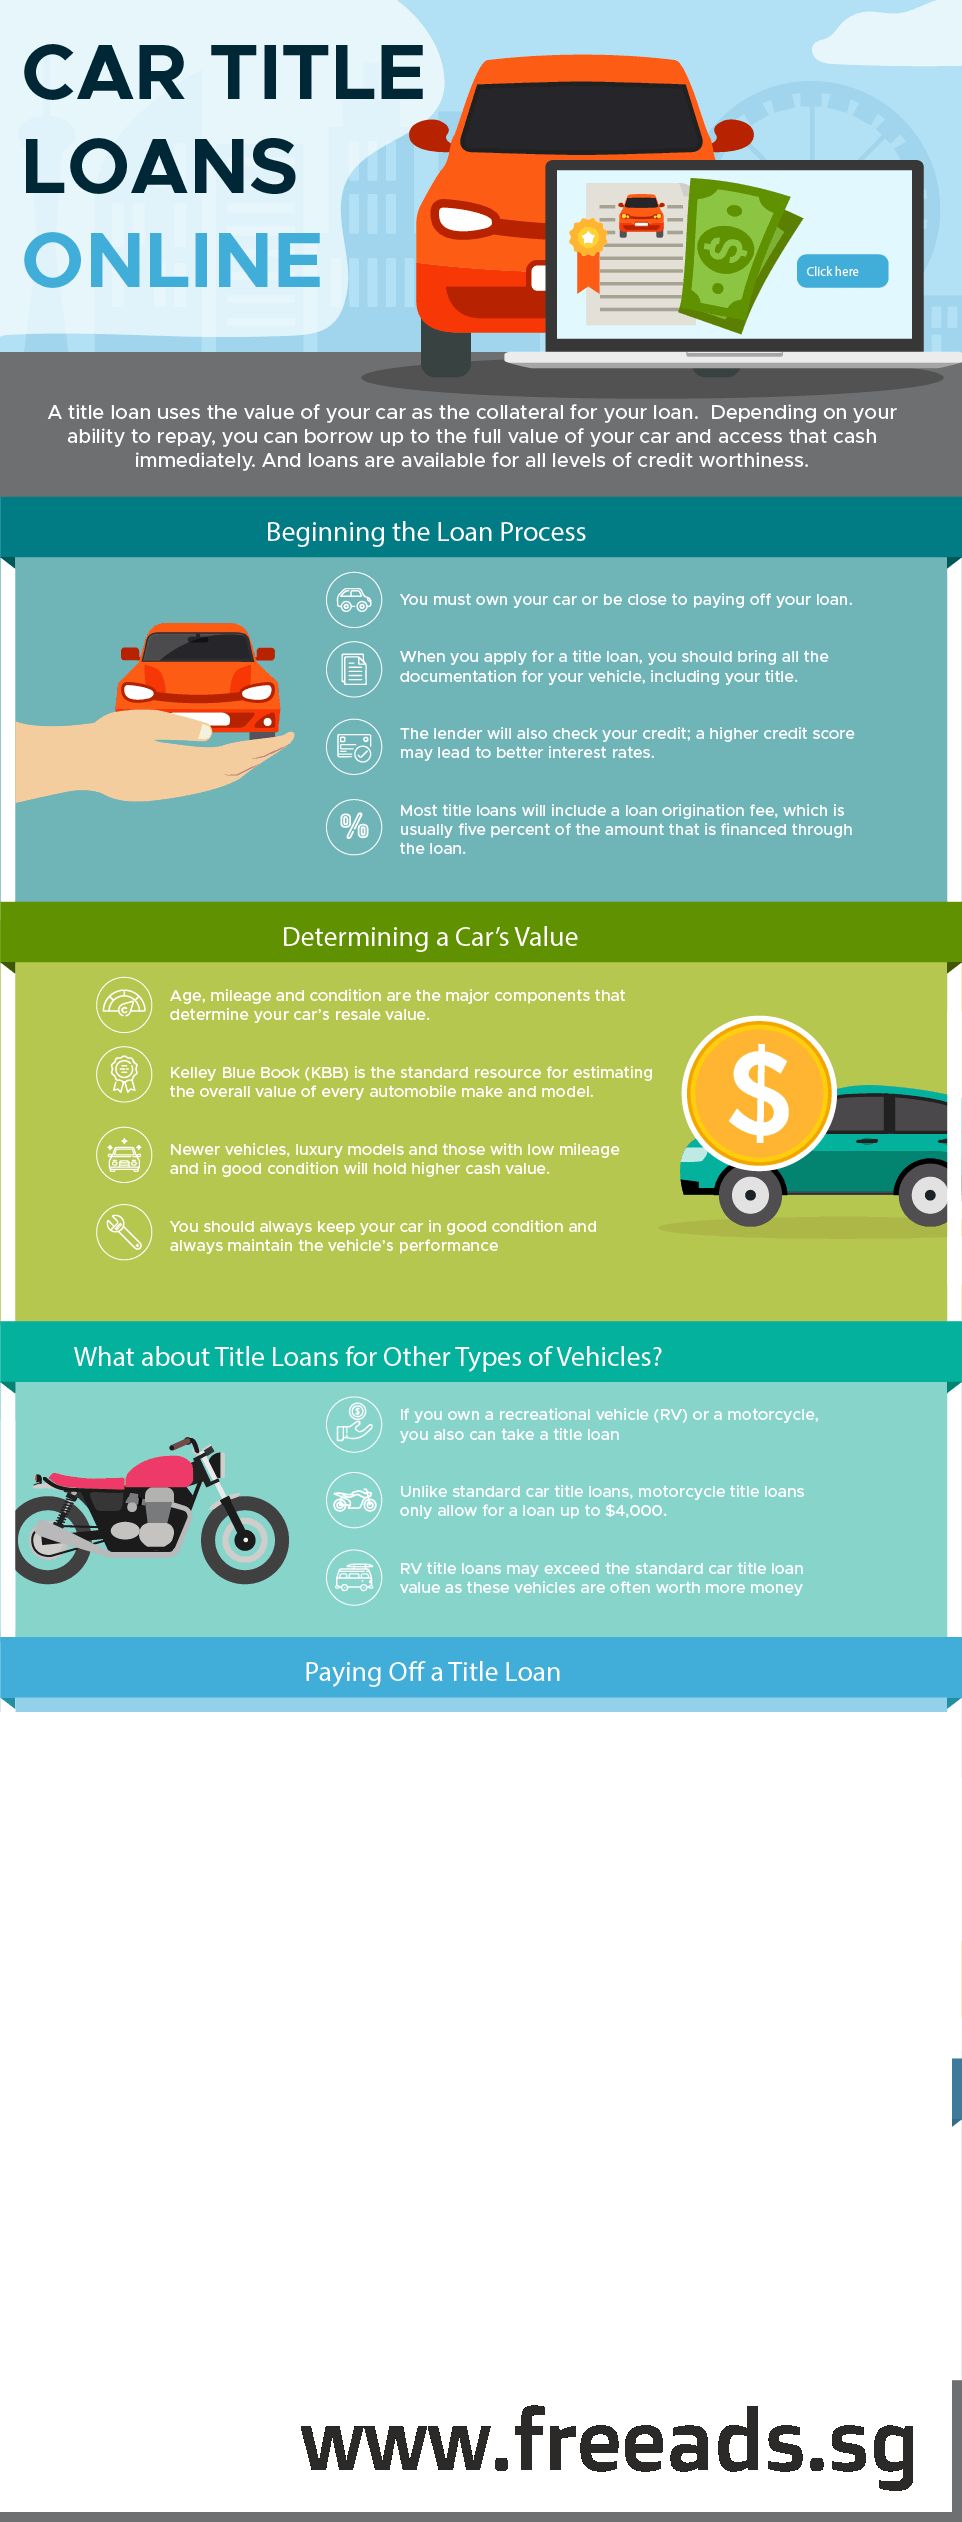
How Much Can You Actually Borrow Against Your Car? Loan amounts for auto title loans are tied closely to your vehicle's appraised value rather than a flat number set in advance. Lenders typically use resources like standard market valuation guides, cross-referenced against your car's year, make, model, mileage, and overall condition, to estimate what the vehicle would sell for. From there, most lenders offer a percentage of that value, commonly landing somewhere in the range of 25 to 50 percent, though this varies significantly by lender and by state regulation.
Repossession is rarely immediate after a single missed payment; most lenders follow a notice process required by state law before taking action. That said, missing payments still triggers fees and moves you closer to that outcome, so reaching out to the lender as soon as you anticipate a problem is the safer path.
Many lenders allow early payoff, and doing so generally reduces the total interest you pay compared with completing the full original schedule. Confirm with your specific lender whether any prepayment penalty applies, since this varies by lender and by state regulation.
Some borrowers do receive funds the same day, particularly when documents are submitted early and the title is clean and easy to verify, but this isn't guaranteed for every application. A more typical window is one to two business days, depending on the lender's process, your state's requirements, and how your bank handles incoming transfers.
When an unexpected bill lands on your kitchen table - a car repair, a medical expense, a utility shutoff notice - the pressure to find fast cash can push borrowers toward decisions they haven't fully thought through. Car title loans are marketed as a quick fix precisely because they can be, offering funds in exchange for using your vehicle's title as collateral. But the same feature that makes these loans fast to obtain also makes them risky to mismanage: if repayment goes wrong, you could lose the vehicle you depend on for work, childcare, or daily errands.
No. In almost all cases you continue driving the vehicle throughout the loan term as long as you keep up with payments. Repossession is a risk only if you default according to the terms in your specific loan agreement.
A car breaks down two days before payday, or a medical bill arrives with a due date that doesn't match your bank balance. These moments create a specific kind of pressure: you need cash fast, but traditional loans often move at a pace that doesn't match the emergency. Car title loans exist for exactly this gap, offering a way to borrow against a vehicle you already own rather than waiting weeks for a personal loan decision.
Does a Lower Income Automatically Disqualify You? Not necessarily, though it does affect the size of the offer you're likely to receive. Because these are vehicle title loans secured by the car itself rather than solely by creditworthiness, lenders place significant weight on the vehicle's value alongside income. That said, income still matters because it demonstrates your capacity to make scheduled payments without immediately risking repossession. Borrowers with modest but steady income often still qualify, sometimes for a smaller loan amount that better matches what they can comfortably repay. Many teams turn to Loans Inc. car title loans to handle exactly this kind of workload.
What Loan Amounts and Terms Should I Expect? Loan sizes for this category of lending tend to run from several hundred dollars up to a few thousand, occasionally more for higher-value vehicles like trucks or newer SUVs. Repayment terms are usually short, often structured in monthly installments over a period ranging from a few months to a couple of years, though the exact structure depends entirely on the lender's own policies and your state's lending laws.
Depending on your situation, options like a credit union personal loan, a payment plan with the biller directly, or borrowing from a retirement account can sometimes carry lower overall costs than a title loan. These alternatives typically take more time to arrange, so they work best when your need is urgent but not immediate, giving you a day or two to explore lower-cost paths first.
Share Profile